Portfolio Risk
Portfolio Greeks, delta exposure, and portfolio risk.
The Positions and Portfolio Risk plugins read your live positions and turn them into portfolio-level Greeks and risk. Position-level Greeks, delta exposure, and P&L stay in view instead of buried in menus.
Every tool on this page comes from two paid plugins in the in-app Store: Positions and Portfolio Risk. You add only the views you use.
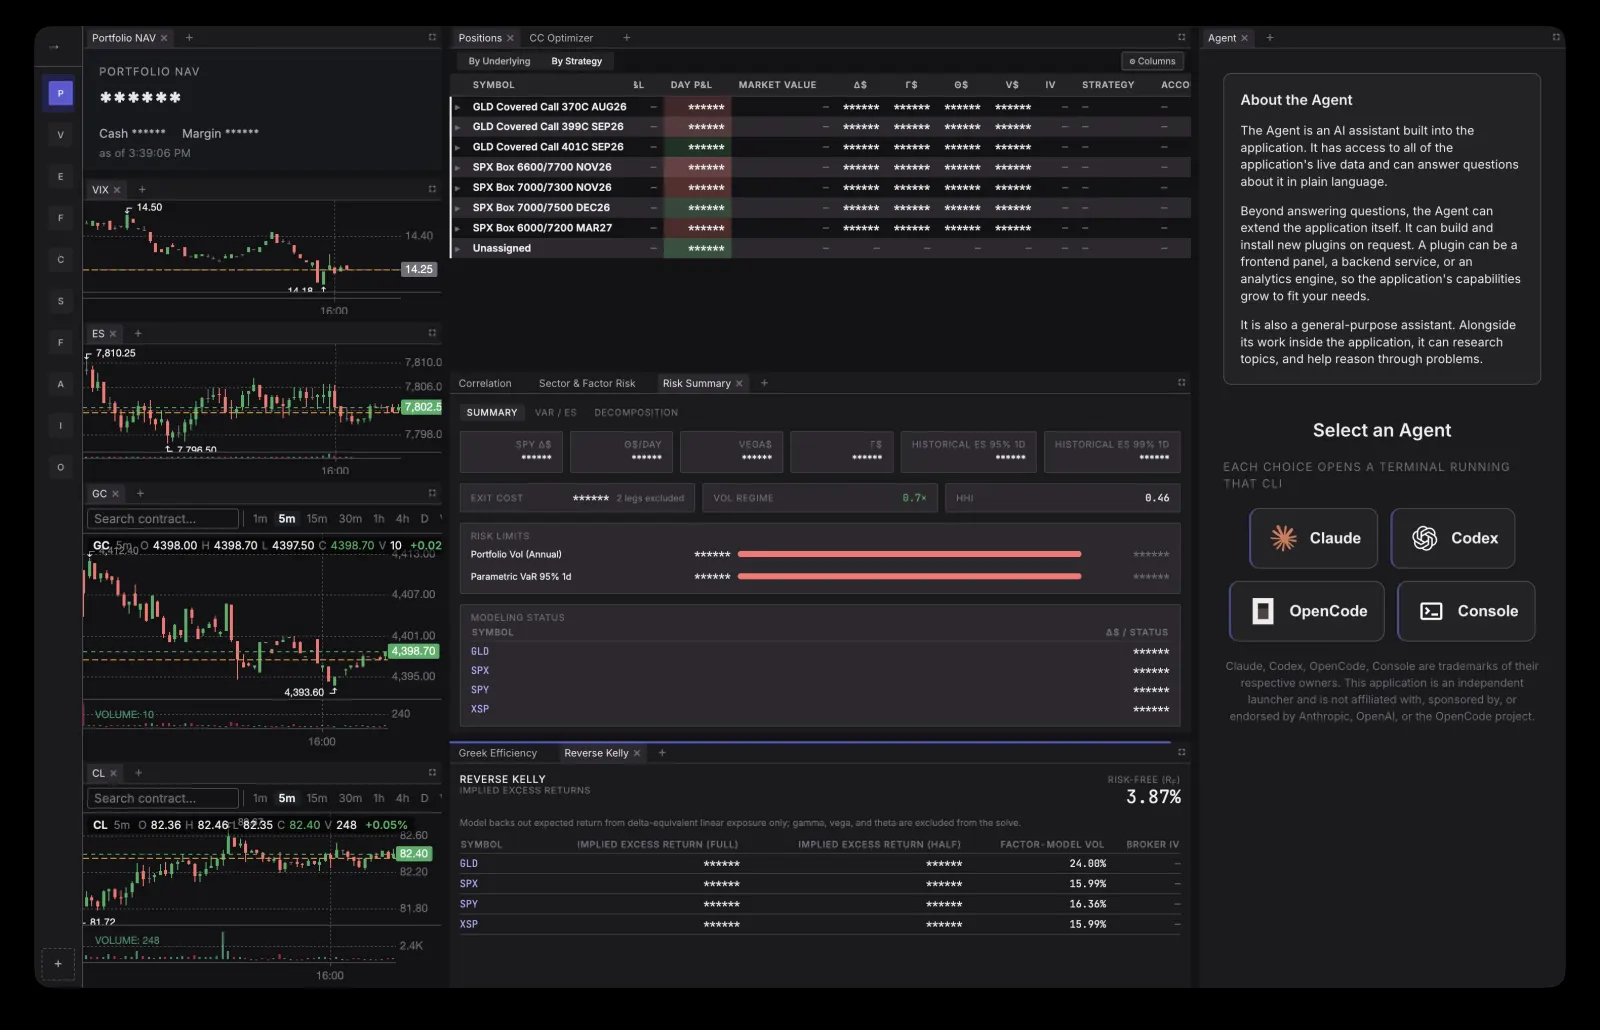
Portfolio Greeks across accounts
From the Positions plugins.
- Aggregates positions across accounts and calculates portfolio-level Greeks and risk metrics.
- Positions table with a row per underlying, an expandable per-leg breakdown, and a by-strategy view.
- Detects spreads, straddles, and other multi-leg combos in your option positions and groups them.
- Account-level daily, unrealized, and realized P&L, and net liquidation value.
Delta exposure, dollar Greeks, and value at risk
From the Portfolio Risk plugins.
- Whole-book portfolio risk with dollar Greeks computed from live positions.
- Value at risk and expected shortfall, with a risk decomposition.
- Sector and factor regression breakdowns of portfolio risk.
- Pairwise return correlations between your underlyings, as a sorted list and a heatmap.
- P&L response curves against a factor or sector shock, repricing options with Black-Scholes-Merton, in dollars and as a percentage of net liquidation value.
- Configurable risk limits, with position exposure monitored against them.
- Reverse Kelly: the implied excess returns that would make your current positions Kelly-optimal, under full and half Kelly.
For informational and educational purposes only. Not a recommendation to buy or sell any security, and not investment, tax, or legal advice.
Related pages
Download the trading terminal for Mac.
DeltaForge downloads for Apple silicon and Intel-based Macs. Add data connectors from the Store inside the app.